
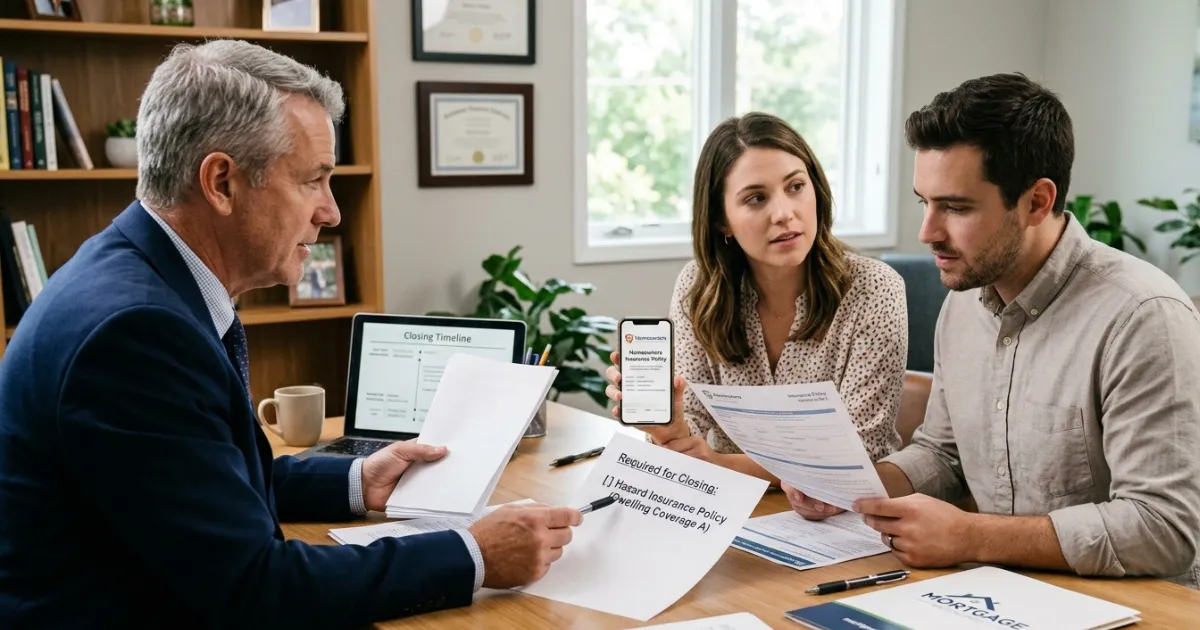
I remember sitting at my first mortgage closing, papers piled everywhere, when the lender slid over a document and said, “You’ll need proof of hazard insurance before we can proceed.” I nodded like I knew exactly what that meant.
I didn’t.
And honestly, you probably don’t either. Not completely, anyway. The term “hazard insurance” shows up in mortgage paperwork, bank emails, and loan agreements all the time. But ask most homeowners what it actually means, and you’ll get a blank stare or a wrong answer.
Here’s the thing: the confusion between hazard insurance and homeowners insurance is one of the most common financial misunderstandings in home buying. And getting it wrong can cost you money, leave you underprotected, or create problems with your mortgage lender.
So let me walk you through this properly, one clear step at a time.
What Is Hazard Insurance, Really?
Let’s start here because this is where most people get confused.
Hazard insurance is not a separate, standalone insurance product. It’s not something you go out and buy on its own. It’s a term (basically a lender’s term) that refers specifically to the dwelling coverage portion of your homeowners insurance policy.
When your mortgage company says “you need hazard insurance,” what they’re actually saying is: “We need you to have coverage that protects the physical structure of the home we’re lending money against.”
Think of it like a slice of pie. Your homeowners insurance is the whole pie. Hazard insurance is just one slice, specifically the slice that covers the building itself against fire, wind, hail, vandalism, and other physical damage.
Actually, let me rephrase that. It’s less like a slice and more like the crust of the pie. It’s the foundational layer that everything else sits on. Without it, the whole financial structure of your home ownership falls apart.
So when your bank asks for hazard insurance, your standard homeowners policy already satisfies that requirement. You don’t need to buy anything extra.
What Does Hazard Insurance Cover?
Because hazard insurance refers to dwelling coverage (Coverage A in insurance terms), it specifically covers damage to the physical structure of your home caused by what insurance companies call “covered perils.”
Here’s what’s typically included:
Fire and lightning including house fires and fire damage from lightning strikes.
Windstorms and hail which matters a lot if you’re in tornado country or the Southeast.
Theft and vandalism covering structural damage caused by break-ins, not just stolen belongings.
Weight of ice, snow, or sleet especially relevant for homes in colder climates.
Explosions usually from gas leaks.
Falling objects like trees or debris after a storm.
Vehicles if a car runs into your home.
Riots or civil disturbances which cause structural damage.
But here’s what hazard insurance does not cover, and this matters a lot financially:
Floods. You need a separate flood insurance policy, either through FEMA’s National Flood Insurance Program (NFIP) or a private insurer.
Earthquakes. These require a separate earthquake endorsement or policy.
Normal wear and tear. If your roof ages out, that’s not a covered event.
Sewer backup. You’ll need a rider or endorsement.
Pest infestations. Termites? Your problem financially.
So if you live in a flood zone and you think hazard insurance has you covered, you’re about to face a very expensive lesson.
What Is Homeowners Insurance and How Is It Different?
Here’s where the full picture comes together.
Homeowners insurance is the complete package. It’s the comprehensive financial protection product that wraps hazard coverage together with several other critical coverages into one policy.
A standard homeowners policy (most commonly the HO-3 policy, which is what most people have) includes six major coverage types:
Coverage A: Dwelling (Hazard Insurance) This is the part your lender cares about. It covers the structure of your home.
Coverage B: Other Structures This covers detached garages, fences, sheds, and similar structures. Usually set at 10 to 15 percent of your dwelling limit.
Coverage C: Personal Property Your furniture, electronics, clothing, appliances. If your home burns down and everything inside is destroyed, this is what pays to replace your stuff.
Coverage D: Loss of Use If your home becomes unlivable after a covered event, this pays for your temporary hotel or rental costs while repairs happen. The other day I spoke with a homeowner whose kitchen fire made the house uninhabitable for four months. Loss of use coverage paid every hotel bill.
Coverage E: Personal Liability If someone slips on your icy porch and sues you, this coverage handles legal defense and settlements.
Coverage F: Medical Payments If a guest gets injured on your property, this covers their immediate medical bills regardless of fault.
So the relationship makes sense now: hazard insurance equals Coverage A. Homeowners insurance equals Coverage A through F, all bundled together.
Hazard Insurance vs Homeowners Insurance: Side-by-Side Comparison
| Feature | Hazard Insurance | Homeowners Insurance |
|---|---|---|
| What it covers | Home structure only | Structure plus belongings, liability, living expenses |
| Who requires it | Mortgage lenders | Lenders and smart homeowners |
| Can you buy it standalone? | Rarely (usually no) | Yes, standard product |
| Covers personal property? | No | Yes (Coverage C) |
| Includes liability protection? | No | Yes (Coverage E) |
| Covers additional living expenses? | No | Yes (Coverage D) |
| Covers floods or earthquakes? | No | No (separate policies needed) |
| Average annual cost | Included in homeowners premium | About $2,543 per year nationally |
The Financial Stakes: Why This Distinction Actually Matters
Look, this isn’t just a vocabulary lesson. The difference between hazard insurance and homeowners insurance has real financial consequences.
If your mortgage lender placed “force-placed insurance” on your home (which happens when you fail to maintain your own homeowners policy), you could end up with coverage that only protects the structure. Nothing else. And force-placed insurance is notoriously expensive and notoriously thin. You’re paying more for less.
Let’s say a fire breaks out and destroys your home. With only hazard coverage, you’d get money to rebuild the structure. But all your furniture, electronics, and personal belongings? Gone. Lawsuit from a contractor injured during rebuilding? You’re personally liable. Hotel bills for six months while the home gets rebuilt? Coming out of your own pocket.
Homeowners insurance prevents all of that from becoming a financial catastrophe.
And the numbers tell the full story. According to 2026 data from Insurance.com, the average homeowners insurance cost nationwide is $2,543 annually for $300,000 in dwelling coverage. That breaks down to roughly $212 per month. For context, the extra coverages beyond just the structure (personal property, liability, living expenses) can increase your premium by 30 to 50 percent compared to structure-only coverage. But that premium increase buys you protection worth many times the cost.
Fair enough, some homeowners look at that number and wince. But consider what you’re protecting. Your home is likely your single largest financial asset.
Why Mortgage Lenders Use the Term “Hazard Insurance”
This is actually the most logical part of the whole story, once you understand it.
Your mortgage lender doesn’t care about your couch. They don’t care about your television, your wardrobe, or your liability exposure. What they care about is the physical building they agreed to finance.
Because here’s the thing: your home is the collateral for your mortgage loan. If you stop paying, the lender needs to be able to sell that home and recover their money. If the home burns down with no insurance coverage, they lose their collateral.
So lenders specifically require hazard insurance (dwelling coverage) because that’s the portion that protects their financial interest in the property. They don’t require personal property coverage or liability insurance because those don’t protect the bank’s investment.
But here’s where it gets practically useful for you: satisfying your lender’s hazard insurance requirement and buying a full homeowners insurance policy are essentially the same thing in practice. Most insurance companies won’t even sell you dwelling-only (hazard) coverage separately. So you get a homeowners policy, and the lender’s requirement is automatically met.
How Much Does Hazard Insurance Cost in 2026?
The cost of hazard insurance isn’t separate from your homeowners policy because it’s built into it. But premium data from 2026 gives us a clear picture of what you’re paying.
According to Insurance.com’s 2026 rate analysis, the national average is $2,543 annually for $300,000 in dwelling coverage. But state-by-state variation is enormous.
Most expensive states for home insurance in 2026:
Florida sits at the top at $7,136 per year. That’s 181 percent above the national average. Hurricane risk and litigation frequency drive those numbers. Louisiana increased dramatically, up 58 percent from 2025 to 2026. Kansas and Oklahoma are also among the most expensive due to tornado exposure.
Least expensive states:
Hawaii averages just $659 per year. Oregon, Utah, Idaho, Nevada, and Wisconsin also rank among the cheapest.
According to a 2026 NerdWallet survey, 34 percent of Americans with homeowners insurance saw their premium increase in the past 12 months. The U.S. GAO also confirmed that nationally, average premiums rose 3 percent from 2019 to 2024 after adjusting for inflation, but in southern coastal areas, increases exceeded 25 percent. It’s like watching a tide slowly rise, you don’t notice it day to day, but after five years you’re standing in water.
Several factors influence your individual premium beyond location. Your home’s age, roof condition, construction materials, proximity to fire stations, local crime rates, your claims history, and even your credit score in most states all feed into the calculation.
What Types of Homeowners Insurance Policies Actually Exist?
Not all homeowners policies are equal. And knowing the difference can save you real money or expose gaps in your coverage.
HO-1 (Basic Form): The most limited option. Covers only 11 named perils. Most mortgage lenders won’t accept it.
HO-2 (Broad Form): Covers 16 named perils. Better than HO-1 but still limited. Rarely sold today.
HO-3 (Special Form): This is the most common homeowners policy in America. And it’s almost certainly what you have. It covers your dwelling on an “open perils” basis, meaning everything is covered unless specifically excluded. Personal property is covered on a “named perils” basis. It includes all six coverage types (A through F).
HO-5 (Comprehensive Form): The broadest coverage available. Open perils for both dwelling and personal property. Best for newer or higher-value homes.
HO-6 (Condo Insurance): Specifically for condo owners. Covers the interior of your unit and personal belongings since the condo association’s master policy covers the building’s exterior.
HO-4 (Renters Insurance): For renters. Covers personal belongings and liability but not the structure.
HO-8 (Modified Coverage): For older homes, typically built more than 40 years ago.
The HO-3 is the sweet spot. It gives you open-perils dwelling coverage (which includes your hazard protection) with personal property, liability, and additional living expense coverage.
Practical Examples That Make It Real
Let me give you three real-world scenarios so this stops being abstract and starts making financial sense.
Example 1: The Kitchen Fire
Maria owns a home in Tennessee and has a standard HO-3 homeowners policy with $350,000 in dwelling coverage. A grease fire starts on her stove, spreads to the cabinets, and causes $48,000 in structural damage. Her personal property coverage kicks in for the $12,000 worth of kitchen appliances and electronics that were destroyed. Her loss-of-use coverage pays for six weeks of hotel stays. Total financial exposure without insurance: $60,000 plus. Her out-of-pocket with insurance: just her $1,000 deductible.
Example 2: The Hailstorm
James lives in Kansas. A severe spring hailstorm tears through his neighborhood and destroys his roof. Damage estimate: $22,000. His hazard coverage (dwelling protection under his HO-3) covers the full repair cost minus his $2,500 deductible. Without homeowners insurance, he’s writing a $22,000 check out of savings.
Example 3: The Lawsuit Nobody Saw Coming
Sarah has a guest visit her home in Colorado. The guest trips on a loose porch step, breaks their wrist, and files a lawsuit seeking $75,000 in medical bills and lost wages. Sarah’s homeowners policy has $300,000 in personal liability coverage. The insurer handles the legal defense and pays the settlement. Without that Coverage E in her policy, Sarah would have faced this personally.
But here’s the thing. None of these people would have been protected by “hazard insurance” alone. All three needed the complete homeowners policy.
What Hazard Insurance Does NOT Cover: The Financial Gaps You Need to Know
So what are you actually exposed to even with a solid homeowners policy? More than most people realize.
Flood damage is the biggest gap. Standard homeowners policies universally exclude flooding. And recent data shows this gap is increasingly costly. Homeowners in flood-prone areas who lack flood insurance face average claim amounts in the tens of thousands of dollars.
Earthquakes require separate coverage or an endorsement. California, Oregon, Washington, and parts of the Midwest are high-risk zones.
Sewer and drain backup is excluded from most standard policies. A sewage backup can cause $5,000 to $30,000 in damage. You can usually add this for $50 to $100 per year.
Mold is often excluded unless it results from a sudden covered event.
High-value items like jewelry, art, or collectibles have sub-limits under standard personal property coverage. If your engagement ring is worth $15,000, your policy might only cover $1,500 of it.
Knowing these gaps isn’t meant to scare you. It’s meant to help you plug them before you need to file a claim.
How to Make Sure Your Coverage Actually Meets Your Lender’s Requirements
Is your mortgage lender going to accept your current homeowners policy as proof of hazard insurance? In almost every case, yes.
Here’s the checklist that makes a strong case:
Your dwelling coverage limit should meet or exceed the replacement cost of your home. Not the market value. The cost to rebuild from scratch with current materials and labor. These two numbers can be very different.
Your policy should name your mortgage lender as an “additional insured” or “loss payee.” This means if there’s a claim payout, the check includes the lender. Most insurers add this automatically during the mortgage process.
Your policy must be active and paid up. Lenders verify coverage, and a lapsed policy can trigger force-placed insurance, which costs you more for less coverage.
You need to provide proof of insurance to your lender at closing and whenever your policy renews.
If you fail to maintain coverage and your lender buys force-placed insurance on your behalf, expect to pay 50 to 200 percent more than what you’d pay for your own policy. And that coverage protects only the structure. Your belongings and liability? Not covered.
Force-Placed Insurance: The Expensive Lesson You Don’t Want to Learn
I mentioned force-placed insurance above, and it’s worth a full explanation because it’s one of the most financially damaging situations a homeowner can find themselves in.
When a lender discovers that your homeowners policy has lapsed or been canceled, they’ll purchase a policy on your behalf and add the cost to your mortgage payment. This forced or “lender-placed” insurance exists to protect the bank’s collateral.
But it’s almost always worse for you in two ways. First, it’s expensive. Sometimes dramatically so. Second, it provides minimal coverage. It basically covers the structure (essentially hazard coverage) and nothing more.
So. You’re paying more for a policy you didn’t choose, that covers less of your actual financial exposure.
The lesson: never let your homeowners policy lapse, even briefly. Set up auto-pay. Update your insurer when you move. And always notify your lender of any insurance changes.
Actual Cash Value vs Replacement Cost Value: A Financial Detail That Changes Everything
Within your homeowners policy (and specifically your dwelling coverage), there’s a distinction that can mean the difference between a check that covers your rebuild and one that leaves you $50,000 short.
Actual Cash Value (ACV) pays the depreciated value of what was lost. If your 15-year-old roof is destroyed, the insurer pays what that 15-year-old roof is worth today, which might be a fraction of what it costs to install a new one.
Replacement Cost Value (RCV) pays what it actually costs to repair or rebuild with new materials. No depreciation deduction.
Most standard HO-3 policies insure dwellings at replacement cost, which is what you want. But personal property is often covered at actual cash value by default. You can usually upgrade to replacement cost coverage for personal property for a modest additional premium.
This distinction matters because when you file a claim, you want money that actually solves your problem, not a check that covers half of it.
Tips to Save Money on Your Homeowners Insurance Without Cutting Dangerous Corners
Homeowners insurance premiums have risen significantly since 2020. Average property insurance premiums have increased by more than 30 percent nationally since then, according to NBER research. But there are legitimate ways to manage your costs without gutting your coverage.
Bundle your home and auto policies. Most major insurers (State Farm, Allstate, USAA, Farmers) offer 10 to 25 percent discounts for bundling.
Raise your deductible strategically. Moving from a $500 to $1,000 deductible typically saves 10 to 15 percent on your annual premium. Going to $2,500 can save about 9 percent more.
Install safety features. Smoke detectors, deadbolts, security systems, and monitored alarm systems often qualify for discounts.
Maintain good credit. In most states, credit score influences your premium. A better credit score generally means a lower rate.
Shop around annually. Getting quotes from at least three insurers every year is the single most effective way to ensure you’re not overpaying.
Avoid small claims. Filing multiple minor claims can raise your rates or even get you dropped. Handle small repairs out of pocket.
Review your coverage limits. Don’t over-insure. If you’ve paid off your mortgage and the land your home sits on is worth $200,000, you don’t need $500,000 in dwelling coverage.
And honestly, the best financial move is to work with an independent insurance agent who can compare multiple carriers. They’re not tied to one insurer, so their goal is matching you with the right policy at the right price.
A Quick Word on Financial Planning and Home Insurance
Home insurance isn’t just a line item in your monthly budget. It’s a core pillar of your personal financial protection strategy.
Think about it this way. You’ve probably got a retirement account, an emergency fund, maybe some investments. But your home is often your single biggest asset. So protecting it with adequate insurance isn’t optional, it’s non-negotiable financial planning.
The risk without it is catastrophic. A fire, a severe storm, a liability lawsuit can wipe out decades of financial progress in a single event.
And the cost of getting it right is remarkably manageable. At roughly $212 per month nationally for solid coverage, you’re paying less than most car insurance premiums to protect an asset worth hundreds of thousands of dollars.
Because when you frame it that way, the math is obvious.
Frequently Asked Questions
Is hazard insurance the same as homeowners insurance? Not exactly. Hazard insurance refers to the dwelling coverage portion of your homeowners policy. Homeowners insurance is the full package, including dwelling, personal property, liability, and additional living expenses coverage.
Can I buy hazard insurance separately? Rarely. In most cases, you can’t purchase standalone hazard or dwelling coverage as a consumer. Most insurers only offer it as part of a complete homeowners policy. The exception is force-placed insurance, which lenders buy on your behalf if your policy lapses.
Does hazard insurance cover floods? No. Flood damage is excluded from standard homeowners and hazard insurance. You need a separate flood insurance policy through FEMA’s National Flood Insurance Program or a private insurer.
How much does hazard insurance cost? Since it’s part of your homeowners policy, the cost is included in your total premium. The national average homeowners insurance premium is $2,543 per year for $300,000 in dwelling coverage, according to 2026 data.
Does hazard insurance cover personal belongings? No. Hazard insurance (dwelling coverage) only covers the physical structure of your home. Personal property coverage, which is a separate component of your homeowners policy (Coverage C), protects your belongings.
What happens if I don’t have hazard insurance and I have a mortgage? Your lender can purchase force-placed insurance at your expense. It typically costs significantly more and provides far less coverage than a standard homeowners policy.
What is Coverage A in homeowners insurance? Coverage A is the formal insurance designation for dwelling coverage, which is the same as what lenders call “hazard insurance.” It covers the physical structure of your home.
Do I still need homeowners insurance if my home is paid off? You’re not legally required to have it once the mortgage is paid off. But it’s still strongly advisable. Your home is a major financial asset, and without insurance, any significant damage comes directly out of your personal finances.
How do I know if my homeowners policy meets my lender’s hazard insurance requirement? Contact your insurer and ask them to list your mortgage lender as a loss payee on your policy. Provide your lender with a copy of your declarations page showing the dwelling coverage amount and policy period. That typically satisfies the requirement.
What is an HO-3 policy? The HO-3 is the most common type of homeowners insurance in the U.S. It covers your dwelling on an open-perils basis (everything unless specifically excluded) and personal property on a named-perils basis. It includes Coverage A through F.